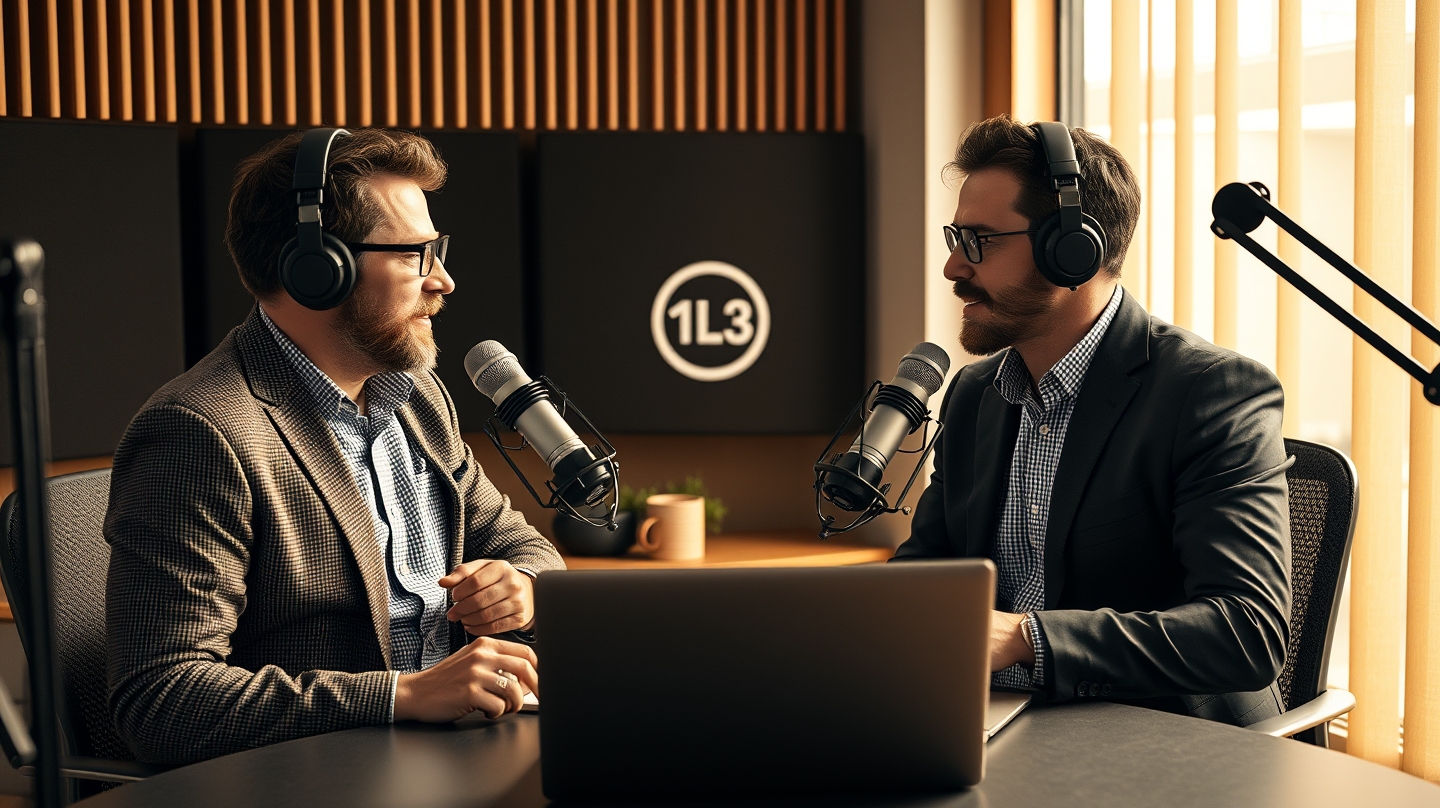
When Zerodha co‑founder Nikhil Kamath and Coinbase chief Brian Armstrong sat down on the “People by WTF” podcast, they didn’t just discuss market trends—they drew a stark parallel between the current AI frenzy and the speculative bubbles of the early 2000s. Their warning centers on a structural cost gap: elite labs such as OpenAI pour billions into proprietary models, while open‑source alternatives, arriving six months later, can be run for a fraction of the price.
Kamath, who built one of India’s largest discount brokerages, argued that shorting every private AI company today could become a profitable strategy in five years. “It feels a bit like the Internet bubble,” he said, suggesting that inflated multiples may evaporate once cheaper models prove sufficient for most commercial workloads.
Armstrong echoed the sentiment, quantifying the disparity. He noted that open‑source inference can be up to 99 % cheaper than running elite models on cloud infrastructure. For price‑sensitive businesses—from e‑commerce platforms to sports analytics firms tracking NBA player performance—this cost differential could shift demand away from high‑priced proprietary solutions toward locally hosted, open‑source stacks.
The implications extend beyond individual investors. If regional ecosystems replicate the Indian scenario Kamath described—building domestic copies of large‑language models that run on locally sourced tokens and energy—the global AI market could fragment. A self‑reliant AI economy would reduce reliance on a handful of U.S. firms, reshaping capital flows and prompting venture funds to reassess exposure to premium AI startups.
From a structural perspective, the market is poised at a crossroads between two futures. On one side, frontier labs retain relevance for highly specialized tasks such as drug discovery or advanced physics simulations. On the other, the bulk of everyday applications—customer service bots, content recommendation engines, and even real‑time game analytics for the NBA—will gravitate toward models that can be deployed on commodity hardware at minimal cost.
This divergence creates a tangible risk for investors who have chased headline‑grabbing valuations without accounting for the looming cost‑driven substitution. History offers a cautionary tale: the dot‑com era saw exuberant pricing collapse, only for a subset of truly valuable companies to survive and later dominate. Armstrong, recalling his experience in the crypto market, warned that “prices correct before real value emerges and growth resumes later.”
For creators and media companies, the shift toward digital‑first distribution amplifies the relevance of cheaper AI tools. Content generators can now leverage open‑source models to produce drafts, subtitles, or even video scripts without incurring prohibitive cloud bills. This democratization may accelerate the creator economy, but it also intensifies competition, forcing premium AI firms to justify higher fees through unique capabilities.
Investors, regulators, and corporate strategists should monitor three emerging signals: (1) the rate at which open‑source models achieve parity in quality; (2) the speed of regional AI talent pipelines that can sustain domestic model development; and (3) the adoption curve among enterprises that prioritize cost over cutting‑edge performance. Each factor will influence whether the current valuation levels are sustainable or poised for correction.
In the short term, we can expect heightened scrutiny of AI funding rounds, with due‑diligence teams demanding clearer pathways to profitability. Longer term, a more diversified AI landscape could emerge—one where high‑margin, niche applications coexist with mass‑market, low‑cost solutions. The balance between these forces will determine the shape of the AI economy over the next decade.